The Corridor Widened Again. The Third Line Fired.
The corridor is the gap between what the US government pays for 2 years and what it pays for 10. A week ago this column measured it at 37.4 basis points and said the back end had refilled it. It has refilled again. The spread closed Friday at 44.7 basis points, and once more the 2yr barely moved while everything from the 5yr out climbed. Strip expected inflation from the 10yr and 2.917% is left, against 2.844% a week ago. That residue is the real yield, and it is what the long end is being paid for. A repricing that lands in rate volatility and leaves equity volatility at the floor is a term premium rather than a policy call. 7 days ago this column named three lines that would settle the read. Two held. The third fired. Ahead: which line, and what credit did when it did.
What moved
The 2yr added 2 basis points on the week to 4.83%. The 5yr added 8 to 5.06%. The 7yr added 11 to 5.17%. The 10yr added 11 to 5.28%. The 20yr added 13 to 5.67%. The 30yr added 14 to 5.63%.
Every point from the 5yr out is in the top few percent of its 3yr range. The 10yr, 20yr and 30yr are all at the 99.4th percentile, the 7yr at the 98.8th and the 5yr at the 98.2nd. The 2yr is at the 87.3rd. The 3-month is at the 30.0th.
2s10s closed at 44.7 basis points, from 37.4. The 10yr cash note closed at 5.277% on Friday and the 30yr at 5.63%.
Away from rates the dollar index added 0.397 on the day and 1.098 on the week to 102.327. USD/JPY took off 0.283 on the day and added 0.311 on the week to 157.644. Gold added $15.10 on the day and $14.60 on the week to $4,177.40. Silver added $1.788 on the day and $0.545 on the week to $61.765. Copper added $0.0865 on the day and $0.028 on the week to $6.5785, in the 93.6th percentile of its range.
The composite headline is +0.353, regime TIGHTENING, on 5 of 5 sub-indices. Rates & Policy is the dominant sub-index at +1.686; Liquidity is the drag at -0.703. The composite is oriented so that a positive reading is stress.
The corridor widened a second week
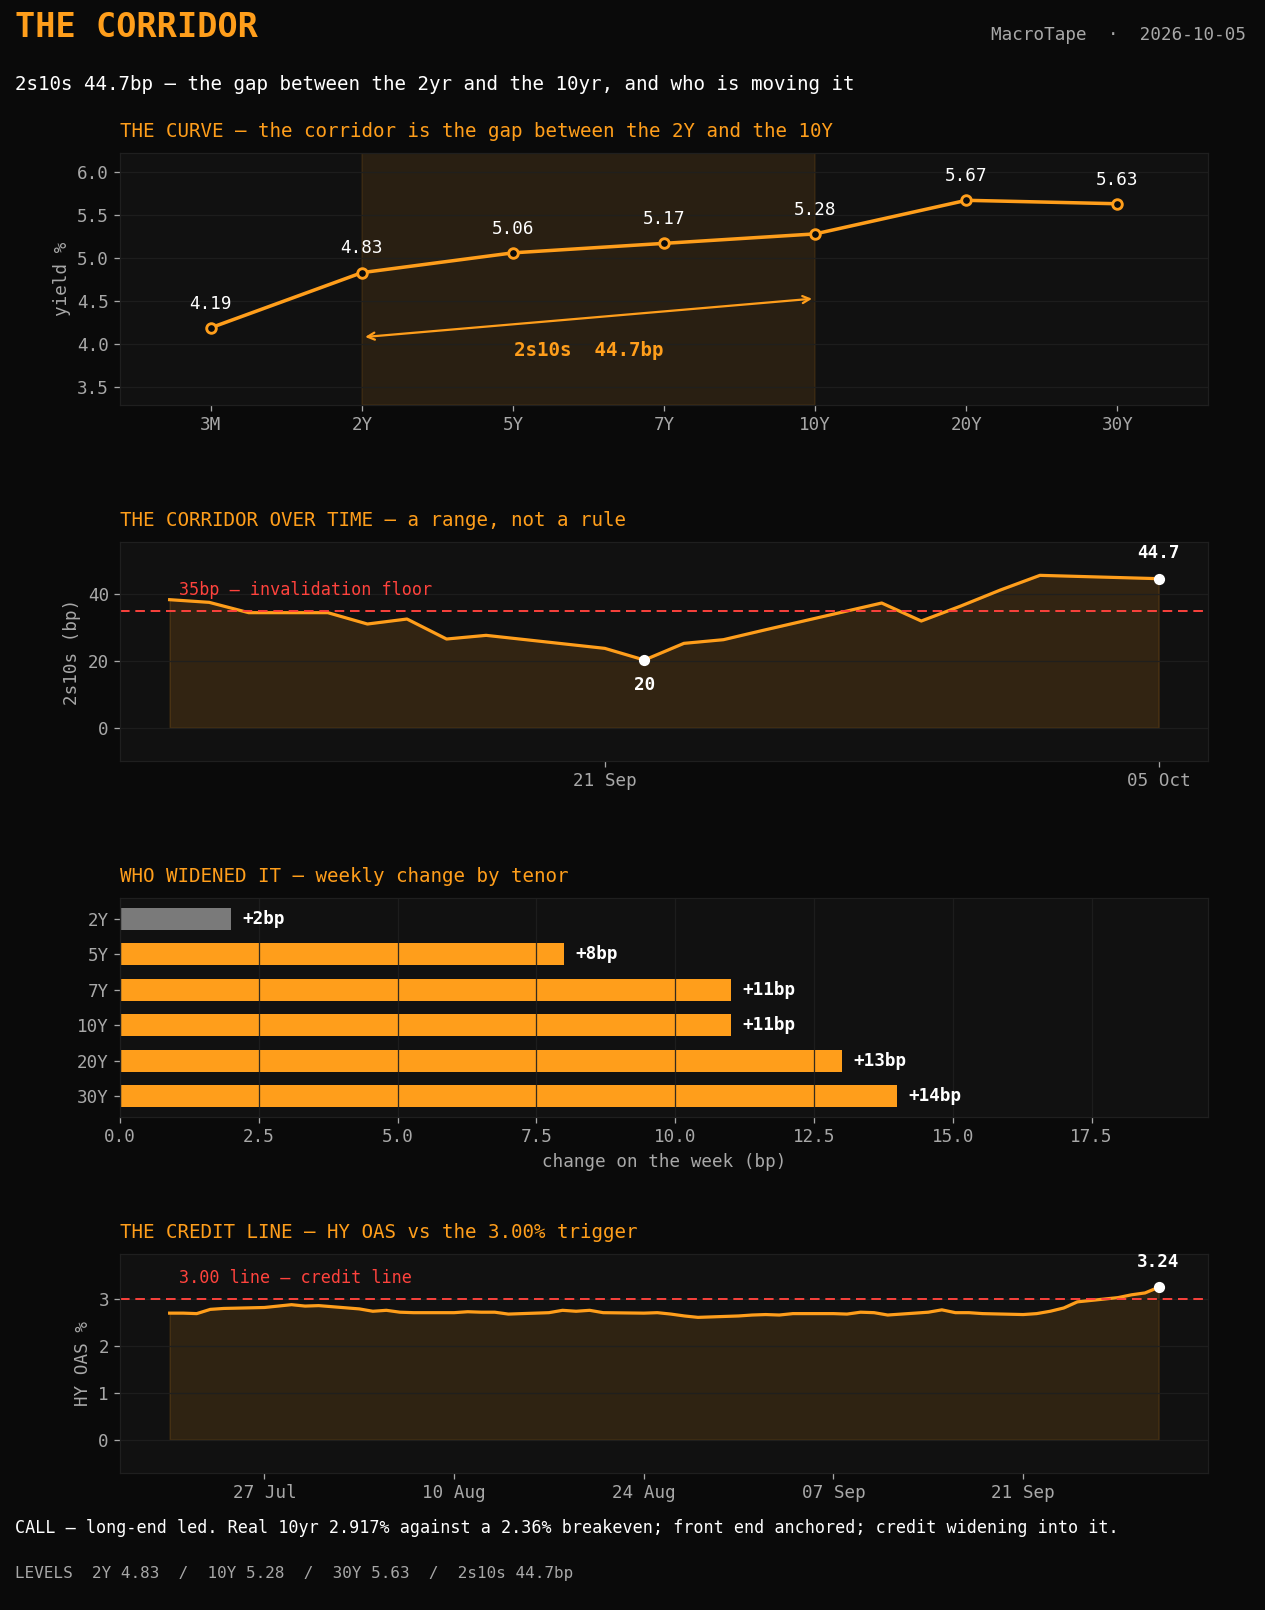
Last Monday this column put 2s10s at 37.4 basis points and called the move bear steepening, long-end led. It named two lines that would falsify the read.
The spread is 44.7 basis points, so the corridor widened rather than closed. The 2yr added 2 basis points while the 30yr added 14. The whole of the net move sits at the back, for a second consecutive week; 7 days ago the 2yr added 5 and the 10yr added 16.
Neither of the two lines fired. 2s10s never fell below the 25 basis points that would have made this a bull steepener, and the 30yr never fell back below 5.45%. It closed at 5.63%.
The third line did fire. 7 days ago this column wrote that high-yield OAS through 3.00% with the 10yr holding above 5.15% would move this from a rates story to a credit story. High yield printed 3.24% on 1 October against a 10yr of 5.28%.
The real yield is still carrying it
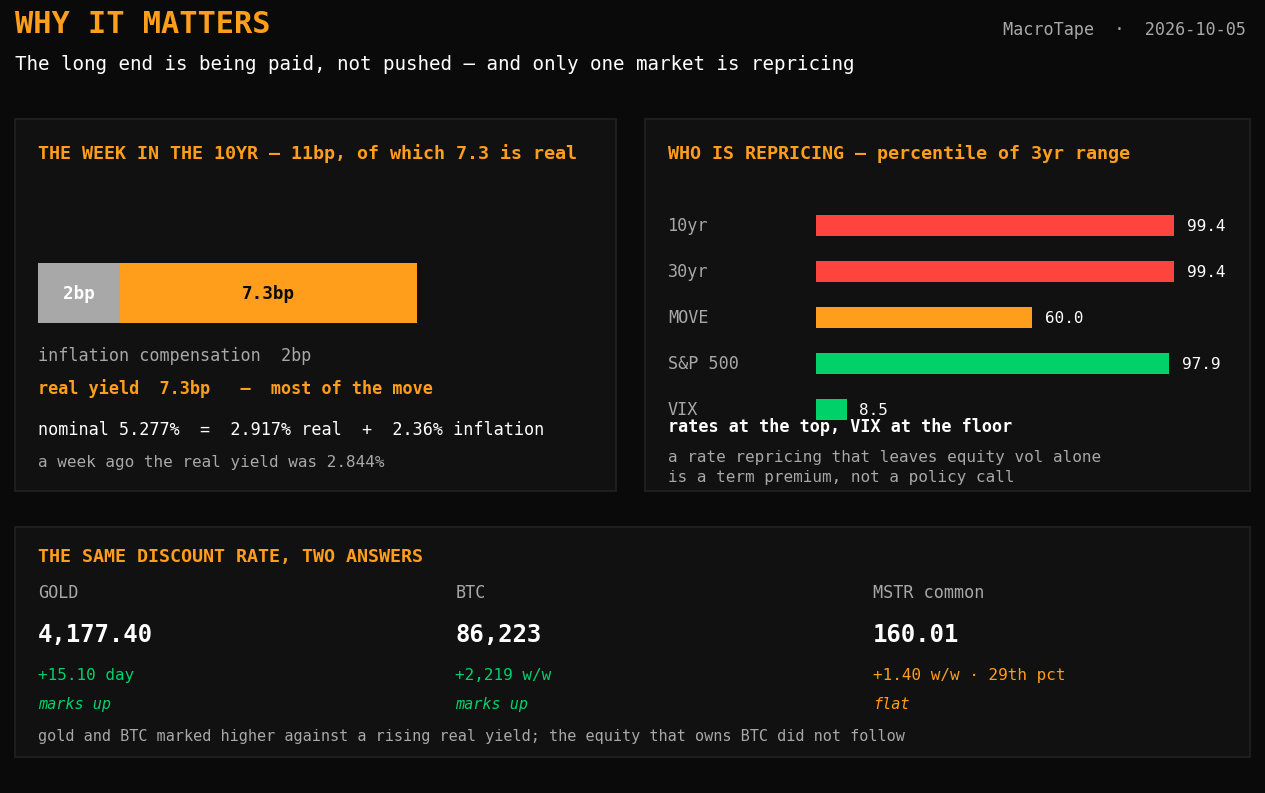
The 10yr cash note is 5.277% on the 2 October close. The 10yr breakeven is 2.36% (as of 2 Oct). That leaves a 10yr real yield of 2.917%.
A week ago the same arithmetic gave 2.844% against a breakeven of 2.34% (as of 25 Sep). The nominal has added about 11 basis points. Inflation compensation has added 2. The other 7.3 are real.
Rate volatility again confirms it. MOVE is 107.29, up 11.29 on the week and in the 60.0th percentile. Equity volatility does not: VIX is 15.31, up 0.44 on the week and in the 8.5th percentile of its range.
Equities are not repricing. The S&P 500 took off 56.27 on the day and 20.69 on the week to 7,722.72, the 97.9th percentile of its range. The Nasdaq 100 added 306.37 on the day and 199.80 on the week to 30,807.93, at the top of its range. TLT took off $0.23 on the day and $1.5218 on the week to $77.48.
A repricing that shows up in the long end of the curve and in rate volatility, and nowhere in equity volatility, is a repricing of the price of duration. That is what a term premium is.
The front end is still anchored
Secured overnight money is 3.87% (1 Oct) against an administered rate of 3.90% (5 Oct), a spread of minus 3 basis points. Effective fed funds is 3.88%.
The 3-month bill yields 4.19% on the 2 October close, at the 30.0th percentile of its 3yr range and 64 basis points below the 2yr.
Reserves are $2,948.1bn (as of 30 Sep). RRP take-up is $1.5bn (as of 2 Oct), from $0.35bn (as of 1 Oct). Treasury's general account is $893.7bn (as of 1 Oct), from $984.0bn (as of 30 Sep).
A front end pricing a policy mistake does not sit 64 basis points underneath the 2yr while overnight secured money prints 3 basis points through the administered rate. The long end is being paid, not pushed.
Credit is no longer the flicker
High-yield OAS is 3.24% (as of 1 Oct), from 3.12% (as of 30 Sep) and 2.66% (as of 21 Sep). That is 58 basis points in 8 sessions. Investment-grade OAS is 0.86% (as of 1 Oct), from 0.84% (as of 30 Sep) and 0.77% (as of 22 Sep).
8 sessions ago this was a widening too small to act on. At 3.24% the high-yield index has cleared the 3.00% line, and it did so with the 10yr above 5.15% rather than below it.
Cash credit has followed. HYG closed at 76.91, off $0.6051 on the week. JNK closed at 92.39, off $0.6841. LQD closed at 101.83, off $0.9366.
The cash flow has not turned with it. Initial claims were 197,000 in the week to 26 September, from 198,000 in the week to 19 September (as of 26 September). Continuing claims were 1,701,000 in the week to 19 September, from 1,712,000 in the week to 12 September (as of 19 September).
Spreads widen before defaults because defaults are the last thing to arrive. Nothing in the labour data yet corroborates 58 basis points of high-yield widening, and that is the normal order rather than a contradiction.
A 2.917% real yield and the BTC complex
BTC is $86,223.17, up $2,219.67 on the week, 2.65% over 5 sessions and 7.74% over thirty. ETH is $2,725.77.
MSTR is $160.01 (as of 2 Oct), up $1.40 on the week and in the 29.1st percentile of its range. The preferreds are mixed: STRF $103.40, off 0.26 on the week; STRK $76.25, up 1.36; STRC $99.41, up 1.3649 and in the 99.7th percentile of its range.
The real 10yr has risen 7.3 basis points in a week, and that is the discount rate on every long-duration claim. BTC marked higher against it, as gold did. The common equity did not follow. That gap is the exposure to watch.
What would change the read
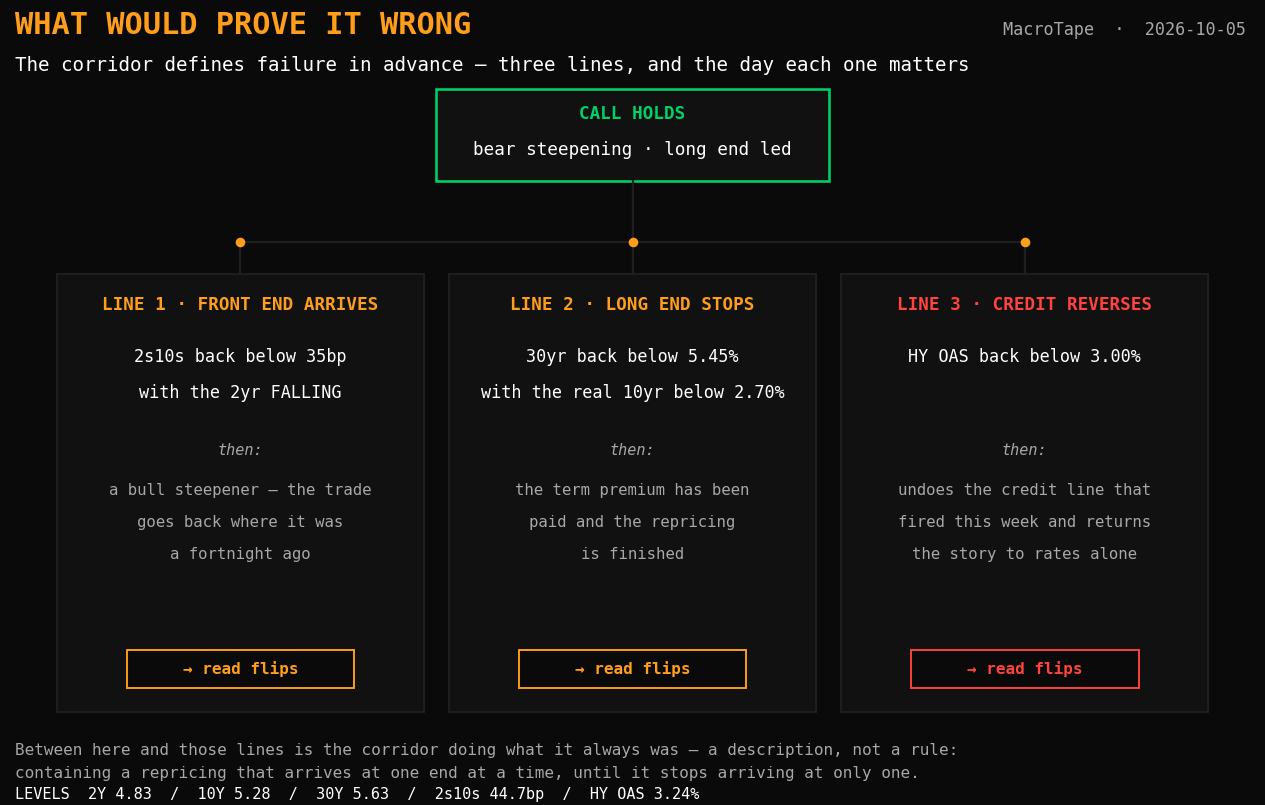
The first break is the front end arriving. 2s10s back below 35 basis points with the 2yr falling is a bull steepener, and it would say the trade has gone back where it was a fortnight ago.
The second is the long end stopping. A 30yr back below 5.45% with the real 10yr below 2.70% would say the term premium has been paid and the repricing is finished.
The third has flipped sides. High-yield OAS back through 3.00% would undo the credit line that fired this week and return the story to rates alone.
Everything between here and those three lines is the corridor doing what it was always a description of rather than a rule: containing a repricing that arrives at one end at a time, until it stops arriving at only one.
| TENOR | LEVEL | 1D Δ | Z (3Y) | RANGE %ILE |
|---|---|---|---|---|
| 2Y | 4.610 | -0.060 | +1.39 | 78 |
| 5Y | 4.780 | -0.070 | +2.24 | 86 |
| 10Y | 4.980 | -0.070 | +2.51 | 84 |
| 30Y | 5.320 | -0.050 | +1.99 | 83 |